Life insurance for people with diabetesYour advocate, not another agent.

One bad offer is not the whole market.

We ask what you need, shop 70+ A+ rated companies, and stay with you as your diabetes gets more controlled. Type 1, type 2, on insulin, or already told no, there is a company that reads your file kindly. Our job is knowing which one.

  • 35+ years in insurance
  • 70+ A+ rated companies
  • Licensed in all 50 states
  • Type 1 and Type 2 diabetes insurable
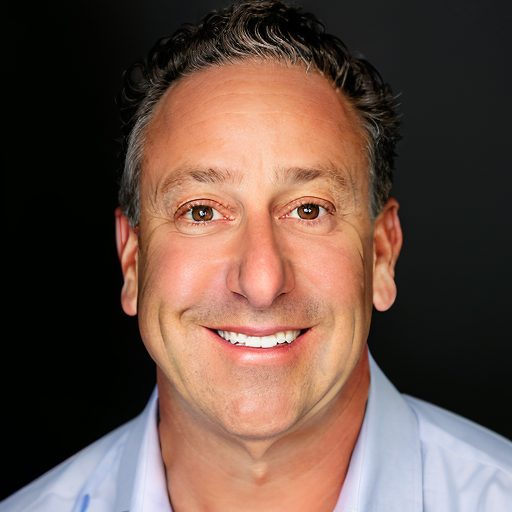
Scott Zimmerman, founder of 1 Stop Diabetic Insurance
Scott Zimmerman
Founder, licensed insurance agent, all 50 states
35+
Years in insurance
50
States licensed
Why this company exists

This isn’t just my job. It’s my family.

My father had diabetes. So did my father-in-law, and my brother-in-law.

Each of them heard that coverage would be hard to get. I helped all three of them, and hundreds, if not thousands, of other families, find the right life insurance to protect the people they love.

When you call, we’re not looking at a file. We take this seriously and work to find the right coverage for you. We’re looking at a person who needs care and wants to cover their loved ones.

Three men who taught me why this matters
  • My fatherDiabetic. Covered.
  • My father-in-lawDiabetic. Covered.
  • My brother-in-lawDiabetic. Covered.

Along the way, I noticed something that still bothers me. Most people with diabetes think they can't get insurance. They were told no once, or twice, or heard it from a friend, and they gave up. And the truth is the opposite of what they were told. There are more good options for diabetic families today than at any other time in the history of this business. Term life. Whole life. Final expense. Long-term care. Real policies, from real carriers, at real rates.

Somebody has to tell people that. Somebody has to answer the phone when a diabetic family finally works up the nerve to ask. That is what this company was built to do.

If you've been told no, tell me. If you never asked because you were sure the answer was no, tell me anyway. There's no cost to the conversation, and you'll walk away knowing more than when you started. That is the whole reason we exist.

Scott Zimmerman
Founder, 1 Stop Diabetic Insurance · Licensed in all 50 states
Have a real conversation Fifteen minutes. No pressure. No sales pitch. Just honest answers about what you and your family qualify for.
A welcome from Scott · 1:39
What we do, and who we do it for.
What we do

It started with his own family. Now it’s his fight for yours.

1 Stop Diabetic Insurance was built to help people with diabetes get really good life insurance, long-term care, and final expense coverage. We shop 70+ A+ rated carriers in all 50 states to find the best coverage for each person’s needs, wants, and situation today.

Press play to hear Scott share why he started helping families with diabetes, and how our team helps. Under two minutes.

Serving families since 1989 · Founded by Scott Zimmerman · NPN 1300464 Scott Zimmerman, licensed specialist Plus our team of specialists
38M+
Americans living with diabetes

You are not the exception. You are the market.

Roughly 38 million Americans live with diabetes. Nearly 100 million more are pre-diabetic. And yet most agents still treat a diabetes diagnosis like an automatic no.

That is the old playbook. In 2026, dozens of carriers write coverage for people with Type 1, Type 2, insulin-dependent, well-controlled, newly diagnosed, and everything in between. The real question is not whether you can qualify. It is which carrier is the right fit for you.

That is the question our team answers every day.

What we cover

Three coverages. One trusted team. Every state.

Most people living with diabetes need more than one kind of coverage. Life insurance for the family. Final expense so no one has to scramble at the worst possible moment. Long-term care for the years ahead. We handle all three under one roof so you never have to tell your medical story three times to three different agents.

01 · Life

Life insurance for people who have diabetes

Term, universal, indexed universal, and whole life from carriers who understand diabetes. Some carriers require no medical exam.

  • Type 1 and Type 2 accepted
  • Insulin-dependent applicants welcome
  • Coverage from $25,000 to $2M+
  • Standard rates possible when diabetes is well controlled (steady A1C, no major complications)
Get me a quote
02 · Final expense

Final expense for peace of mind

Small whole-life policies designed to cover burial, funeral, and end-of-life expenses. Most applications don't require a medical exam.

  • Coverage from $15,000 to $100,000
  • Guaranteed-issue options if declined elsewhere
  • Rates locked for life
  • Approvals from immediate to 72 hours
See your options
03 · Long-term care

Long-term care planning

Traditional LTC, hybrid life/LTC, and asset-based LTC solutions for diabetic applicants who plan ahead.

  • Traditional LTC for controlled diabetics
  • Hybrid policies
  • We represent most major A+ rated long-term care companies
Explore LTC options
Why 1 Stop

Three things our clients tell us they wish every agent did.

Specialists, not generalists.

Most agents have little experience writing insurance for people with diabetes. Our team writes them every week. That means we already know which carrier says yes at your A1C, on your medication, at your age, before an application is ever submitted.

Honest first, sales second.

If the coverage you asked about isn’t the right fit, we’ll show you what you can get instead. If we can’t help, we’ll tell you, and share any other options we know of. No pressure. Ever. That’s a promise.

All three products, one conversation.

Life, final expense, and long-term care under one roof. You share your history once. Our team does the shopping across 70+ A+ rated carriers and brings back the plan that actually fits your family.

How it works

From first call to peace of mind in five steps.

Every family is different. The five steps are the same. Most of our clients go from the first conversation to a policy in the mail inside two to four weeks. No pressure at any stage. You move at the pace that feels right.

1

The intake call

Fifteen to twenty minutes. We listen more than we talk. We ask about your diagnosis, your family, and what you are hoping to protect.

2

We shop the market

Our team shops your case across 70+ A+ rated carriers and identifies the two or three most likely to say yes at the best rate for your situation.

3

Honest quote review

You see real numbers, real carrier names, and the honest tradeoffs. No fine print buried for later. You decide what fits, or if the timing is not right.

4

Simple application

Most policies use tele-underwriting. That means no paramedical exam, no needles, no home visits. Roughly twenty minutes of your time.

5

Family protected

Coverage in force. Documents in your inbox and your mailbox. We stay your point of contact for the life of the policy. Any question, any year, you call us.

Free checklist

Seven questions to ask before you apply for any policy.

Click below for a free checklist for anyone dealing with a diabetes diagnosis.

Read it before you talk to any agent, ours or anyone else's. A good agent will be glad you asked.

Get the Free Checklist
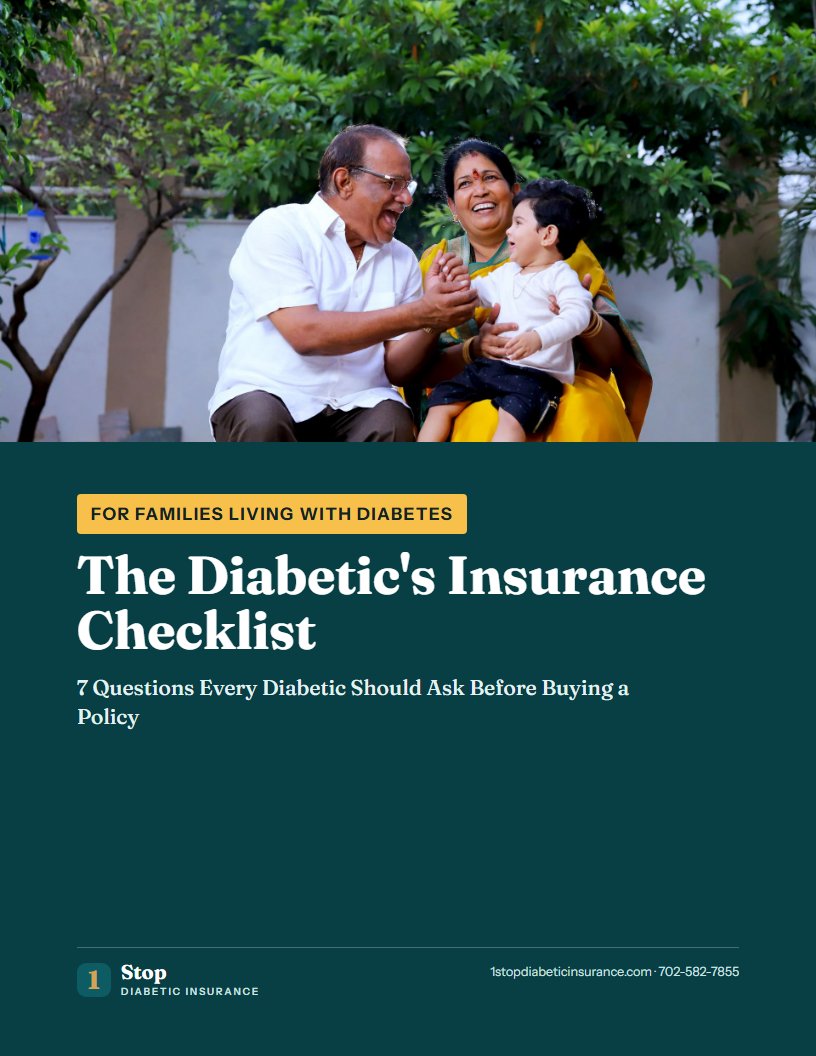
Cover of The Diabetic's Insurance Checklist: 7 Questions Every Diabetic Should Ask Before Buying a Policy
Reach out to us

Get a quote. Ask a question. Or just tell us what you've been through.

Fill out the form and someone from our team will call you back within one business day. Prefer to talk right now? The phone number below rings straight through to our team.

Most first conversations are fifteen to twenty minutes. We ask about your diagnosis, your family, and what you've already been told. You leave the call knowing more than you did going in, whether or not we ever do business together. That is a promise, and it's the whole reason this company exists.

Prefer to talk right now?
702-582-7855
Visit us
3145 St. Rose Parkway, Suite 200
Henderson, NV 89052

Send us a message

Fill in whatever you're comfortable sharing. Only your name and email are required.

Your information is used only to shop coverage on your behalf. It is not sold and is not protected health information (HIPAA). Rates and eligibility depend on carrier underwriting; not everyone will qualify.

Common questions

The answers we give on almost every first call.

If your question is not below, ask us on the phone. There is no such thing as a dumb question about protecting the people you love.

I have Type 1 diabetes. Can I still get coverage?

Yes. Type 1 is the hardest case in the diabetic-insurance world, and it's the one we spend the most time on. Life insurance is available for most Type 1 applicants from a specific set of carriers. Final expense options are open to almost everyone with a Type 1 diagnosis. Long-term care is the toughest, but not off the table: a small number of carriers still write traditional LTC for well-managed Type 1 applicants, and when traditional LTC declines, hybrid life-and-LTC and asset-based LTC solutions often become the answer.

The specific carriers, the specific rates, and the specific tradeoffs depend on your age, your control, and your history. That's exactly what the first call is for.

Can I get life insurance if I have Type 2 diabetes?

In most cases, yes. Carriers look at your A1C, your medications, how long you've had the diagnosis, and whether you have any complications. Well-controlled Type 2 diabetics can often qualify for standard or preferred rates. Even applicants with higher A1C or insulin dependence usually have options.

I was declined already. Should I even bother?

Yes, and here's why: most declines happen because the wrong carrier was chosen for the applicant, not because the applicant is uninsurable. Different carriers evaluate the same medical history very differently. We routinely place coverage for clients who were declined by other agents, sometimes at better rates than the original applicant was quoted.

What A1C level disqualifies me?

There is no single number that disqualifies you across the board. Different carriers set different thresholds, usually somewhere between 7.5 and 10 for standard fully-underwritten policies. Above that, no-exam and guaranteed-issue options open up. The point of an initial call is to figure out where you land, and which carrier writes best at your number.

Does Ozempic or Mounjaro affect my rates?

Newer GLP-1 medications like Ozempic, Mounjaro, and Wegovy are actually being viewed favorably by many carriers in 2026, because they demonstrate active management. What matters more is your A1C trend, weight, and whether the medication was prescribed for diabetes or for weight loss. We'll walk through your specific situation on the call.

Do I need a medical exam?

It depends on the policy. Guaranteed-issue and simplified-issue policies, including most final expense plans, require no medical exam at all. Many modern fully-underwritten life insurance policies use tele-underwriting: a 20-minute phone interview and a records check instead of an exam.

Some carriers, and some larger coverage amounts, still require a paramedical exam. We'll tell you upfront which category applies to your case. If an exam is needed, we'll arrange for it at your home at no cost.

How much does this cost me?

Our consultation is free. Our quote is free. If you buy a policy, our compensation comes from the carrier, at no extra cost to you. The premium you pay is the same whether you buy through us or directly from the insurance company. The difference is that we shop 70+ A+ rated carriers for you instead of one.

Reach out. Ask a question. See what's actually possible.

Whether you're ready to apply or just looking around, we would rather hear from you. Fifteen minutes on the phone, a message through the form, a question over email. Whatever is easiest. You'll walk away knowing more than when you started, and there is never a cost to the conversation.